Pebble's pitch deck is a masterclass in narrative-driven fundraising, dedicating half of its slides to establishing a systemic problem before introducing the solution. The company raised $6.2M in 2023 by targeting the inefficiencies of the 1970s-era banking system, specifically citing the low 0.4% APY of average checking accounts and the $290 in annual fees paid by the average American family. The solution centers on a 'financial super app' that offers 5% APY through USDC lending and 5% cash back at major merchants like Amazon and Uber. While the deck is light on technical architecture and re…
Key takeaways
- The deck identifies a specific market pain point by noting that the average American checking account offers only 0.4% APY (Slide 2).
- Pebble positions digital 'neobanks' as marketing facades built on top of the same outdated 1970s infrastructure they claim to disrupt (Slide 3).
- The core product value proposition is a 5% APY yield generated through off-chain USDC lending partnerships (Slide 7).
- The startup offers a high-incentive rewards program with 5% cash back at 55 merchants, including Amazon, Uber, and Chipotle (Slide 7).
- Pebble introduces a blockchain-based rewards system called 'Pebbles' designed to be spendable outside their own ecosystem, unlike traditional Amex points (Slide 8).
- The team slide emphasizes founder pedigree, highlighting that both founders are Y Combinator alumni from UC Berkeley (Slide 9).
- The deck omits standard financial metrics such as CAC, LTV, current user growth, or a specific funding ask amount.
- Reported data indicates the company successfully raised $6.2M in a Seed round in 2023 following this presentation (Business Insider).
The Narrative of Disruption: Pebble's 10-Slide Strategy
Pebble’s pitch deck is a concise, high-conviction document that leans heavily into the 'anti-bank' sentiment prevalent in the fintech and crypto sectors. Rather than leading with complex technical diagrams of blockchain architecture, the deck focuses on the consumer experience and the financial math that makes traditional banking unattractive to modern users. By the time the reader reaches the solution, the founders have already framed the entire existing banking industry as a 'lie' built on 'crumbling foundations.'
Slide 1: The Team Introduction
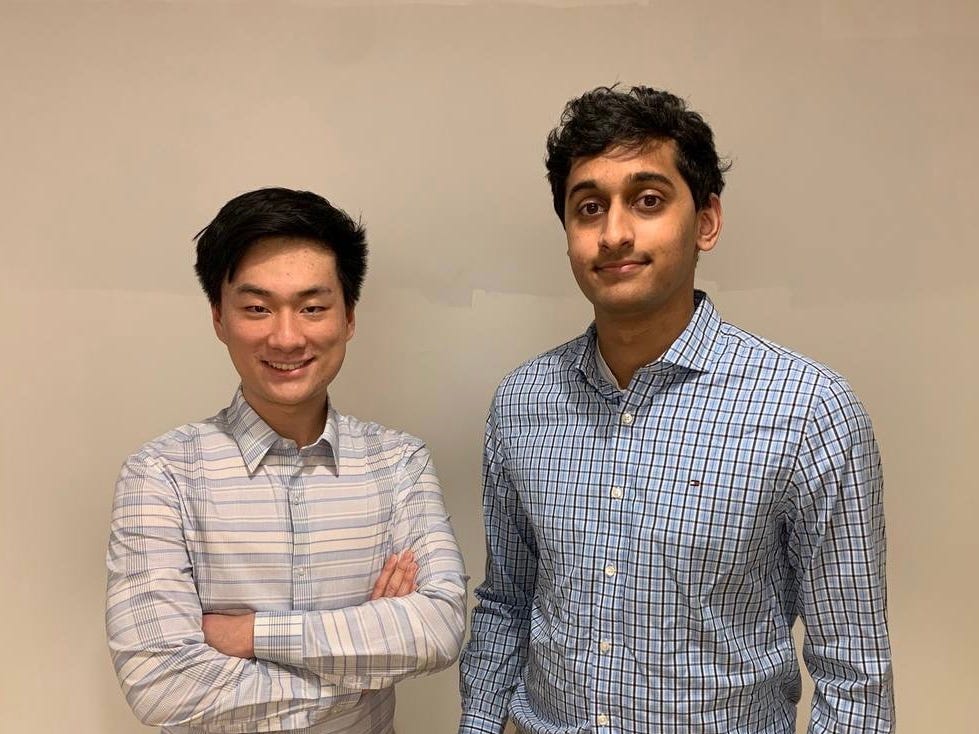
The deck opens not with a logo, but with a full-page photo of the founders, Aaron Bai and Sahil Phadnis. This is a common tactic for early-stage startups where the 'who' is often more important than the 'what.' It establishes a human connection immediately before diving into the technical and systemic problems of the banking world.
Slide 2: The Failure of Traditional Banking
Slide 2 serves as the 'Problem' slide, but it uses hard data to make its case. It lists four specific grievances: the average checking account gives 0.4% APY, the average credit card gives 1% cash back, the average family pays $290 in annual fees, and the system is plagued by credit checks and wire fees. By citing these figures, Pebble sets a low bar for their own product to clear. The slide concludes with a strong emotional hook: 'Banks haven't done anything but hold us back.'
Slide 3: The Attack on Neobanks
In a strategic move, slide 3 differentiates Pebble not just from 'old' banks, but from 'digital' banks like Chime or Revolut. It labels them as 'marketing companies' that act as proxies for old banks. This is a critical distinction for investors; Pebble is claiming to build new infrastructure rather than just a prettier user interface for an existing bank. They argue that neobanks pay partnership fees with investor money, implying that their own model is more sustainable or fundamentally different.
Slide 4: The Inflation Context
Slide 4 ties the company's mission to the macro-economic climate. It notes that inflation has risen to levels not seen since 1981. This creates a sense of urgency—'People need better financial tools NOW.' By positioning the app as a hedge against inflation, Pebble moves from being a 'nice-to-have' savings app to a 'must-have' financial survival tool.
Slide 5: The Trade-Off Argument
This slide highlights the friction in current financial products. It asks rhetorical questions about why users can't have high returns and the ability to pay bills simultaneously. It frames the industry as 'blatantly inconvenient,' setting the stage for Pebble to be the 'all-in-one' solution that eliminates these compromises.
Slide 6: The Financial Super App
Slide 6 introduces the solution: Pebble. It defines the product as a 'financial super app' that allows users to save, spend, and send money from a single balance. This is the pivot point of the deck, moving from the systemic failures of others to the specific promise of the Pebble ecosystem.
Slide 7: The Value Proposition
This is the 'meat' of the deck. Slide 7 lists six key features that differentiate the product:
5% APY through off-chain USDC lending desks. · The ability to pay bills using crypto. · Unlimited 5% Cash Back at 55 merchants (Amazon, Uber, etc.). · Payroll connection. · 100% free model. · The first USDC debit card.
This slide is designed to overwhelm the reader with value. By offering 5% yield and 5% cash back, Pebble is positioning itself as significantly more lucrative for the user than the 'average' stats cited on slide 2.
Slide 8: The 'Pebbles' Rewards System
Slide 8 explains the 'moat' and the unique technology. It introduces 'Pebbles,' a blockchain-based rewards system. It compares this to Amex points, noting that while Amex locks you in, Pebbles are 'permissionless' and spendable anywhere, including the metaverse. This uses blockchain not just as a buzzword, but as a mechanism for consumer freedom, which aligns with the 'anti-bank' theme of the earlier slides.
Slide 9: Founder Pedigree
The penultimate slide reinforces the team's credibility. Both Aaron Bai and Sahil Phadnis are listed as Y Combinator Founders and UC Berkeley graduates (Economics/CS and EE/CS respectively). For a Seed round, this level of pedigree often offsets the lack of detailed financial projections or a long track record for the specific company being pitched.
Slide 10: Closing
The final slide is a simple brand reinforcement, mirroring the minimalist aesthetic of the rest of the deck.
What Pebble's Deck Does Well
Strong Antagonist: The deck identifies a clear 'villain' (the 1970s banking system) and a 'fake hero' (neobanks). This narrative structure makes the solution feel inevitable and necessary.
Quantifiable Comparisons: By listing the 0.4% APY of traditional banks against their own 5% APY, the founders make the value proposition easy to understand without needing a deep dive into the underlying tech.
Focus on Benefits, Not Tech: While the product is powered by USDC and blockchain, the deck focuses on what the user gets (cash back, yield, no fees) rather than how the smart contracts work. This is essential for a consumer fintech pitch.
What Is Missing from the Pebble Deck
Regulatory Strategy: Offering 5% yield through USDC lending is a high-risk area from a regulatory standpoint (as seen with companies like BlockFi or Celsius). The deck does not address how Pebble navigates SEC or banking regulations.
Unit Economics: The deck claims the product is '100% free' and gives 5% cash back. It does not explain how the company makes money or how it sustains such high rewards without burning through investor capital indefinitely.
Traction Metrics: There is no mention of user numbers, waitlist size, or transaction volume. Even for a seed round, some indication of early market interest is usually expected.
The Ask: The deck does not state how much money is being raised or what the specific milestones are for the next 18 months. While Business Insider reported the raise was $6.2M, that information is not present in these slides.
Lessons for Founders
1. Use the 'Contrast' Method: If your product offers a better rate or lower fee, put the industry average on a slide early on. It makes your 'Solution' slide hit much harder.
2. Narrative Over Data: At the Seed stage, you are selling a vision. Pebble spends 50% of the deck on the 'Why' before showing the 'What.' This builds a logical bridge that makes the investor want the solution to exist before they even see it.
3. Leverage Your Pedigree: If you have YC or top-tier university backing, don't hide it. Pebble places their founder slide at the end to leave a lasting impression of competence and 'bankability.'
Frequently asked questions
- How does Pebble generate a 5% APY for its users?
- According to slide 7, Pebble generates this yield through 'exclusive partnerships with off-chain USDC lending desks.' The app converts user deposits into the USDC stablecoin and lends it to institutional firms to capture higher returns than traditional savings accounts.
- What makes Pebble's rewards program different from traditional credit cards?
- Slide 8 explains that traditional rewards, like Amex points, are locked within a single ecosystem. Pebble's 'Pebbles' are built on the blockchain, making them 'permissionless' and spendable anywhere, including pizza shops or the metaverse, even if a customer leaves the platform.
- Who are the founders of Pebble and what is their background?
- As shown on slide 9, the company was founded by Aaron Bai (CEO) and Sahil Phadnis (CTO). Both are UC Berkeley graduates and former Y Combinator founders, providing the 'founder-market fit' signal often required for large seed rounds.
- Which merchants are included in the Pebble cash-back program?
- Slide 7 lists 55 merchants where users can receive unlimited 5% cash back. Specific examples provided in the deck include Amazon, Uber, Chipotle, and Southwest Airlines.
- Does the deck include a roadmap or financial projections?
- No. The 10-slide deck is focused entirely on the problem, the high-level solution, the rewards ecosystem, and the team. It lacks a roadmap, go-to-market strategy, financial projections, or a slide detailing how the $6.2M will be spent.